Published · Carbon3
What the GHG Protocol is revising
The GHG Protocol’s Corporate Standard, Scope 2 Guidance and Scope 3 Standard are being revised and brought together in a consolidated corporate standard. A separate workstream covers actions and market instruments. It deals with how a company reports the outcome of projects and certificates, such as energy attribute certificates or book and claim certificates, that may not be reflected in its physical inventory. The GHG Protocol has worked in partnership with ISO since September 2025 on aligned standards.
Where the actions and market instruments work stands
- A white paper set out options for reporting actions and market instruments. It is a basis for discussion, not a draft standard.
- A request for information ran from 31 March to 31 May 2026 and received almost 500 responses.
- Preliminary feedback supported a multi-statement approach, with a physical inventory, a separate market-based inventory and an actions statement for outcomes outside the inventory.
- The workstream’s formal public consultation is planned for 2027.
| Estimate | Step |
|---|---|
| Q2 2027 | Consultation draft of the consolidated standard |
| Q4 2028 | Revised standard published |
What this means for companies now
Until the revision is complete, the current standards apply. Scope 3 is calculated under the Scope 3 Standard published in 2011, and its rules on what may change a company’s inventory have not been replaced. Frameworks that refer to the GHG Protocol, including ESRS E1, SBTi and California’s SB 253, will follow its changes.
How this connects to insetting on Carbon3
Inset credits are one of the instruments this work will address. Until the GHG Protocol decides, reporting inset credits separately from the physical inventory, with their evidence, is consistent with the direction of both the GHG Protocol’s feedback and SBTi V2.0.
Carbon3 keeps that evidence with each credit. It covers the project, the independent verifier’s report, issuance to the project developer, the funders and every transfer and retirement. See Insetting 101 and the methodology.
Questions
Has the GHG Protocol published a draft standard on market instruments?
No. It has published a white paper and run a request for information. A consultation draft of the consolidated corporate standard is estimated for the second quarter of 2027.
When will the revised GHG Protocol standards be published?
The Standard Development Plan of 29 July 2026 estimates the revised consolidated standard for the fourth quarter of 2028.
Sources
- GHG Protocol, Actions and Market Instruments Standard. White paper, request for information, consultation planning
- GHG Protocol, key standard development updates: FAQ. Preliminary feedback on the white paper
- GHG Protocol, Consolidated Corporate Standard: Standard Development Plan (29 July 2026). Consultation draft Q2 2027; revised standard Q4 2028
- GHG Protocol, Corporate Value Chain (Scope 3) Accounting and Reporting Standard
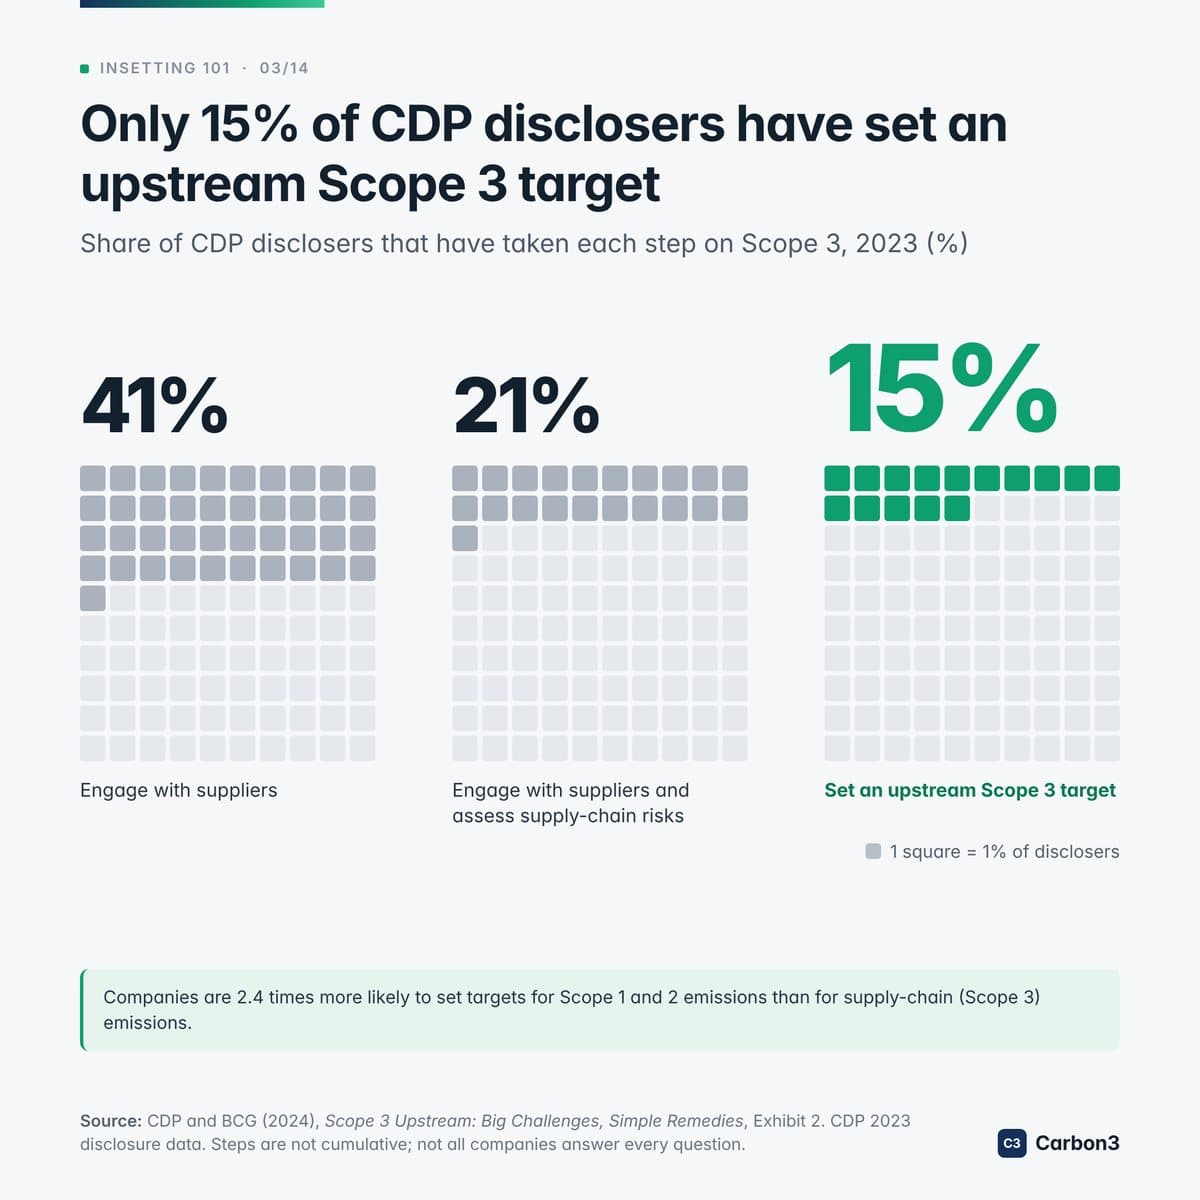
- CDP and BCG, Scope 3 Upstream: Big Challenges, Simple Remedies (2024), press release. 41%, 21% and 15%
Read next
The Carbon3 Newsletter
Weekly analysis of industrial decarbonization and insetting across Scope 1 to 3, from the Carbon3 team.