The Cement & Concrete Outlook 2026
Low-carbon cement is not a technology problem. The final investment decision is missing because the green premium has no buyer.
By Carbon3 team1 min read
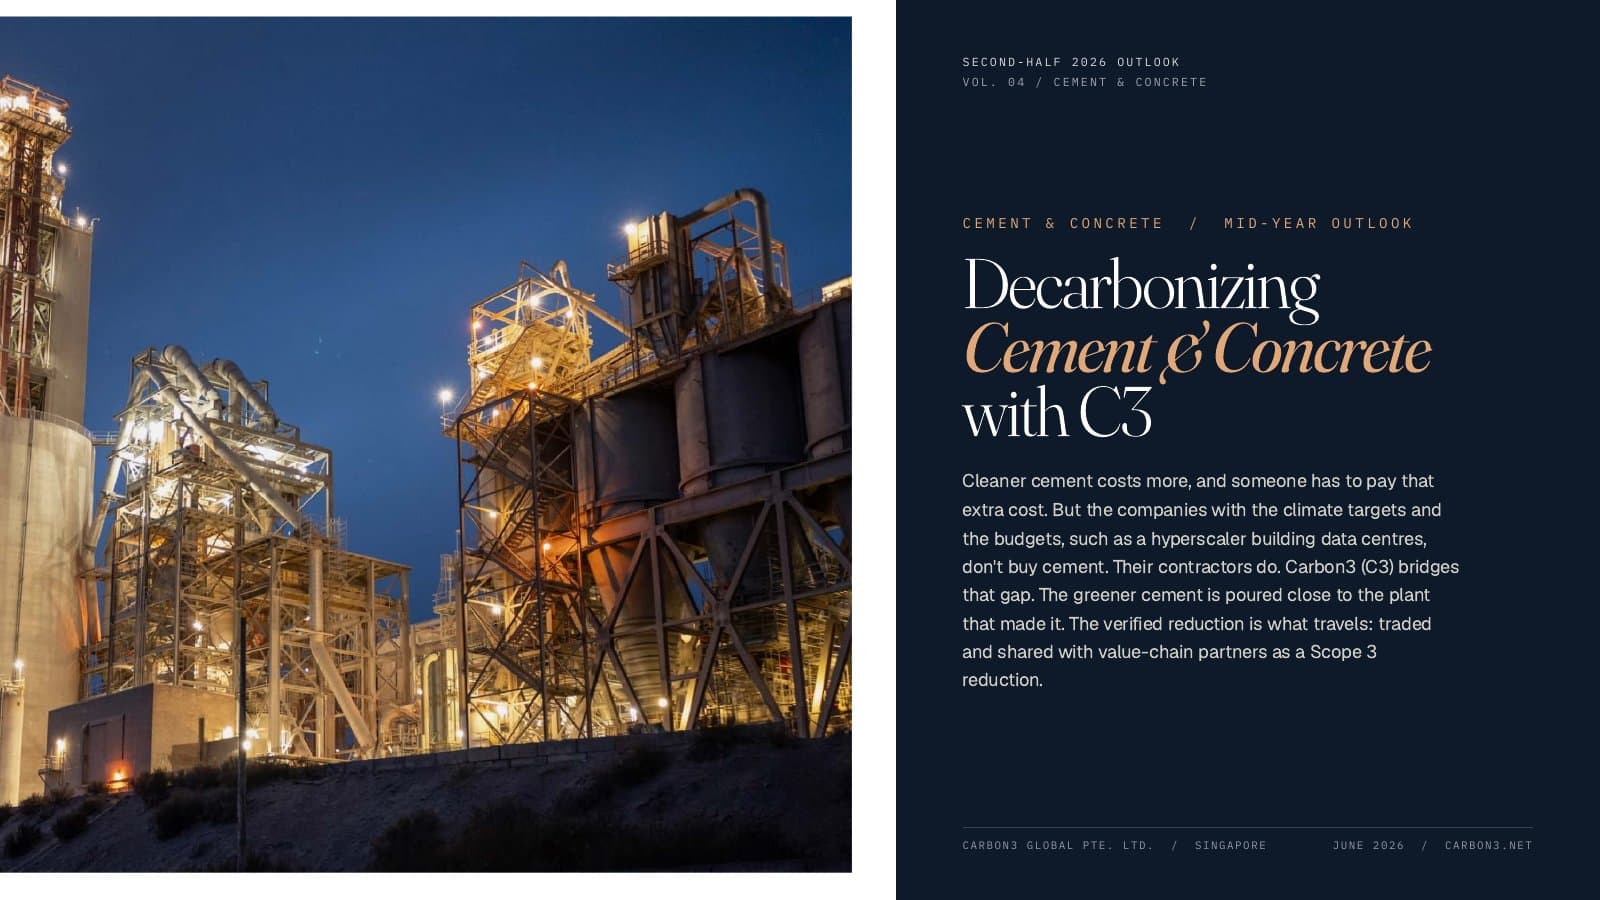
Our 2026 Sustainable Cement & Concrete Outlook
For builders, infrastructure developers, or real estate owners, cement and concrete sit squarely in Scope 3 emissions, often dominating corporate carbon footprints and among the toughest to reduce. From January 2026, those embedded emissions will carry a direct price at the EU border under CBAM. The pressure to act is real and rising.
Low-carbon cement is not primarily a technology problem. Proven pathways, from clinker substitution and alternative fuels to CCUS and novel binders, already exist, and pilot plants are demonstrating near-zero carbon concrete.
Demand & finance have to lead. GCCA says CCUS must deliver +30% of the net-zero pathway. No producer has full transition readiness yet. The question is no longer whether to decarbonize, it’s who captures the value as the sector cleans up, and who pays the carbon bill.
What’s missing is the final investment decision, because the green premium still lacks buyers ready to underwrite it at scale. This report maps the 2026 landscape and shows how Carbon3 closes the gap equitably.
Authors: Ilja Nevolin, Paul Cruickshank, Chris Chatterton
GCCA, Global Cement and Concrete Association International Energy Agency (IEA)
Document
The full document, as a PDF
Free to download once you have a free account. No payment details are needed.
Originally published on LinkedIn, 15 June 2026.
The Carbon3 Newsletter
Weekly analysis of industrial decarbonization and insetting across Scope 1 to 3, from the Carbon3 team.
Read more from the research team.
Outlook
The Iron & Steel Outlook 2026
The furnace already works.
Read the articleOutlook
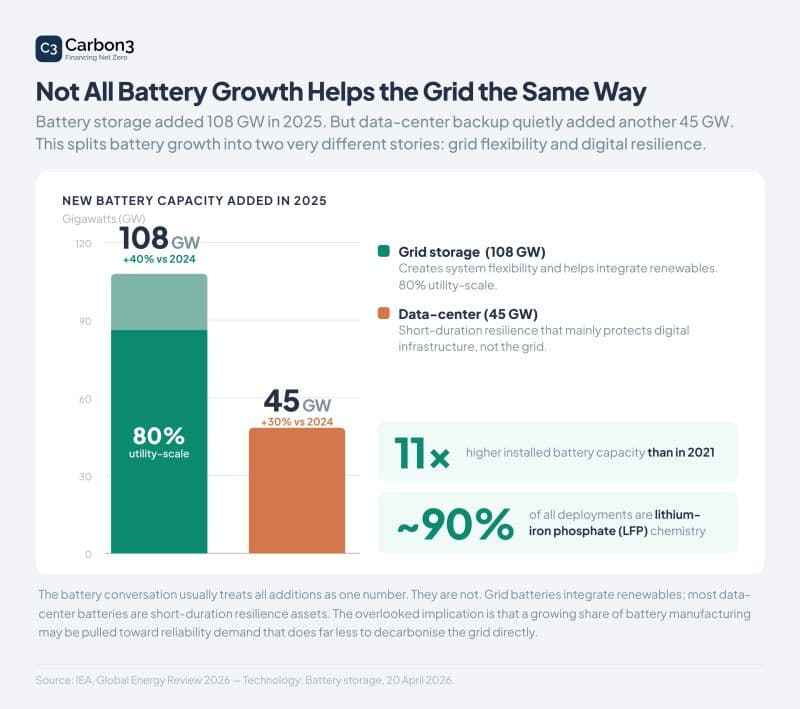
The battery boom is no longer one story
Grid-scale storage is scaling fast, while data centers add backup capacity to protect uptime rather than to make the grid more flexible.
Read the articleOutlook
The Aviation Outlook 2026
Clean jet fuel is not a technology problem.
Read the article
See the companies behind these figures in the Data Hub.
Look up your suppliers’ emissions and targets, free.