Climate risk now carries a cost. Supply chain resilience can lower it.
Bloomberg finds companies with higher physical climate exposure face a 22 bps increase in WACC.
By Carbon3 team4 min read
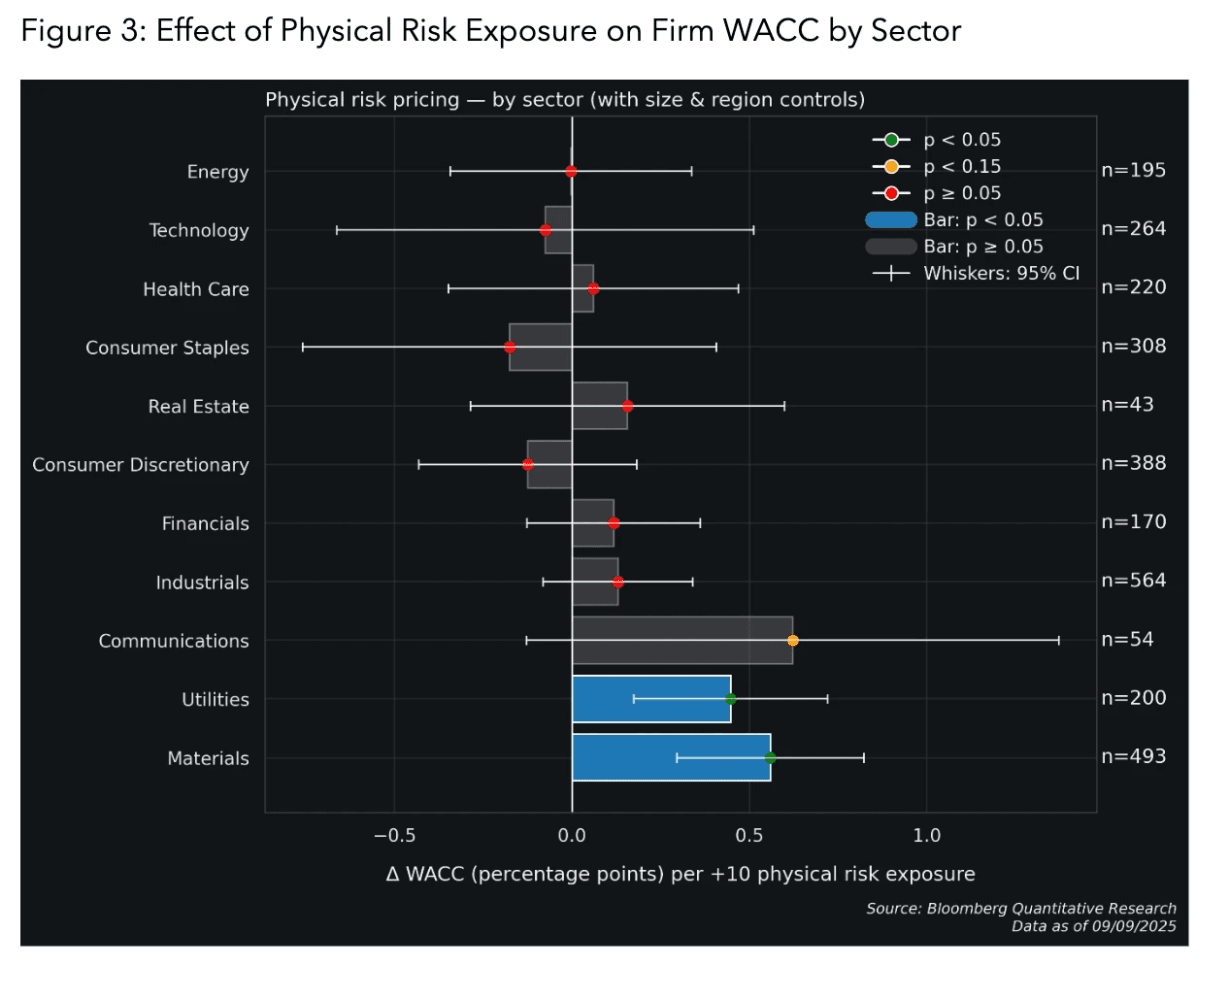
Recent research from Bloomberg Professional Services, in collaboration with Riskthinking.AI, has confirmed what many sustainability and finance leaders have long suspected: markets are already pricing physical climate risk into the cost of capital.
Across nearly 3,000 listed firms worldwide, Bloomberg et. al. found that companies facing 10 percentage points more physical-risk exposure carry, on average, a +22 basis-point increase in Weighted Average Cost of Capital (WACC), even after adjusting for size, region and sector. That’s a measurable financing premium for climate vulnerability.
The effect isn’t uniform. It is strongest within asset-intensive sectors such as Materials (+56 bps) and Utilities (+45 bps), and most pronounced in Latin America (+94 bps) and Asia (+25 bps) (see charts below). These are key industries that form the backbone of global supply chains - steel, cement, shipping, power generation, and heavy manufacturing. Additionally, these are all sectors where Carbon3 is focused on incentivizing and scaling supply chain decarbonization.
Source: Bloomberg Professional Services, "Does Physical Climate Risk Carry a Financing Premium?" (October 2025). (c) Bloomberg Finance L.P., 2025.

Source: Bloomberg Professional Services, "Does Physical Climate Risk Carry a Financing Premium?" (October 2025). (c) Bloomberg Finance L.P., 2025
From climate exposure to cost of capital
The implications are clear: physical climate risk is no longer an abstract ESG metric; it is a direct financial variable. Higher exposure means higher financing costs, tighter margins, and diminished competitiveness.
Conversely, companies that can demonstrate climate resilience through transparent disclosure, credible adaptation plans, and verified emission-reduction activity can begin to reverse that premium. In other words, resilience now has a return.
Bloomberg’s study concludes that “corporates [...] demonstrating resilience to physical risk – through disclosure of climate risk assessments and clear adaptation plans – [...] may be able to lower their financing costs moving forward.” That is a financial case for proactive decarbonization.
How Carbon3 helps lower that premium
Carbon3 provides a verifiable, monetizable mechanism for companies to demonstrate and finance supply-chain decarbonization and resilience. Our platform enables firms to:
-
Quantify and certify Scope 3 reductions through insetting credits generated within their own value chains.
-
Monetize those reductions, turning verified climate action into tradable financial assets.
-
Disclose credible progress toward net-zero in ways that investors, lenders, and auditors can trust.
By embedding emissions reductions directly into supply-chain contracts, Carbon3 helps industrial actors transform climate performance from a cost center into a measurable financial advantage, effectively reducing the WACC penalty highlighted in Bloomberg’s findings.
For investors and lenders, these verified insetting credits offer a data-rich signal of lower transition risk. For issuers, they provide tangible evidence of operational resilience and a pathway to more favorable financing terms. For credit holders, they provide additional returns as tradeable assets that may appreciate in value. And if the credit holders are the original firms that are making their supply chains more resilient, that's a double return: a reduced WACC from recognition of greater supply chain climate resilience, and a revenue stream from traded credits.
Why this matters now
The sectors most affected by the new climate-risk premium - Materials, Utilities, Transport, and Manufacturing - are also those under growing pressure from regulators, customers, and financiers to decarbonize. In Asia and Latin America, where the financing penalty is highest, the opportunity to lead on verified insetting and resilient supply-chain projects is particularly strong.
Carbon3’s mission is to bridge these worlds: connecting industrial decarbonization projects with financial markets that increasingly reward resilience and penalize inaction.
A new equation for capital markets
In this new framework, higher climate risk = higher cost of capital. Conversely, verified resilience = lower cost of capital. Carbon3 enables companies to move from the first equation to the second, turning credible, quantified climate action into measurable financial performance. Putting sustainability into your supply chain isn't just for ESG reports or siloed sustainability teams' performance metrics - it is central to the financial success of industrial firms worldwide.
Work with Carbon3 to realize new returns
If you operate in materials, utilities, or other asset-intensive sectors, or invest in those who do, the cost of capital is already reflecting your climate exposure. Connect with Carbon3 to explore how verified insetting and supply-chain resilience can protect value, unlock new financing opportunities, and deliver measurable climate impact.
(Based on Bloomberg Professional Services: “Does Physical Climate Risk Carry a Financing Premium?” October 2025. © Bloomberg Finance L.P.)
Originally published on LinkedIn, 24 October 2025.
The Carbon3 Newsletter
Weekly analysis of industrial decarbonization and insetting across Scope 1 to 3, from the Carbon3 team.
Read more from the research team.
Transition finance
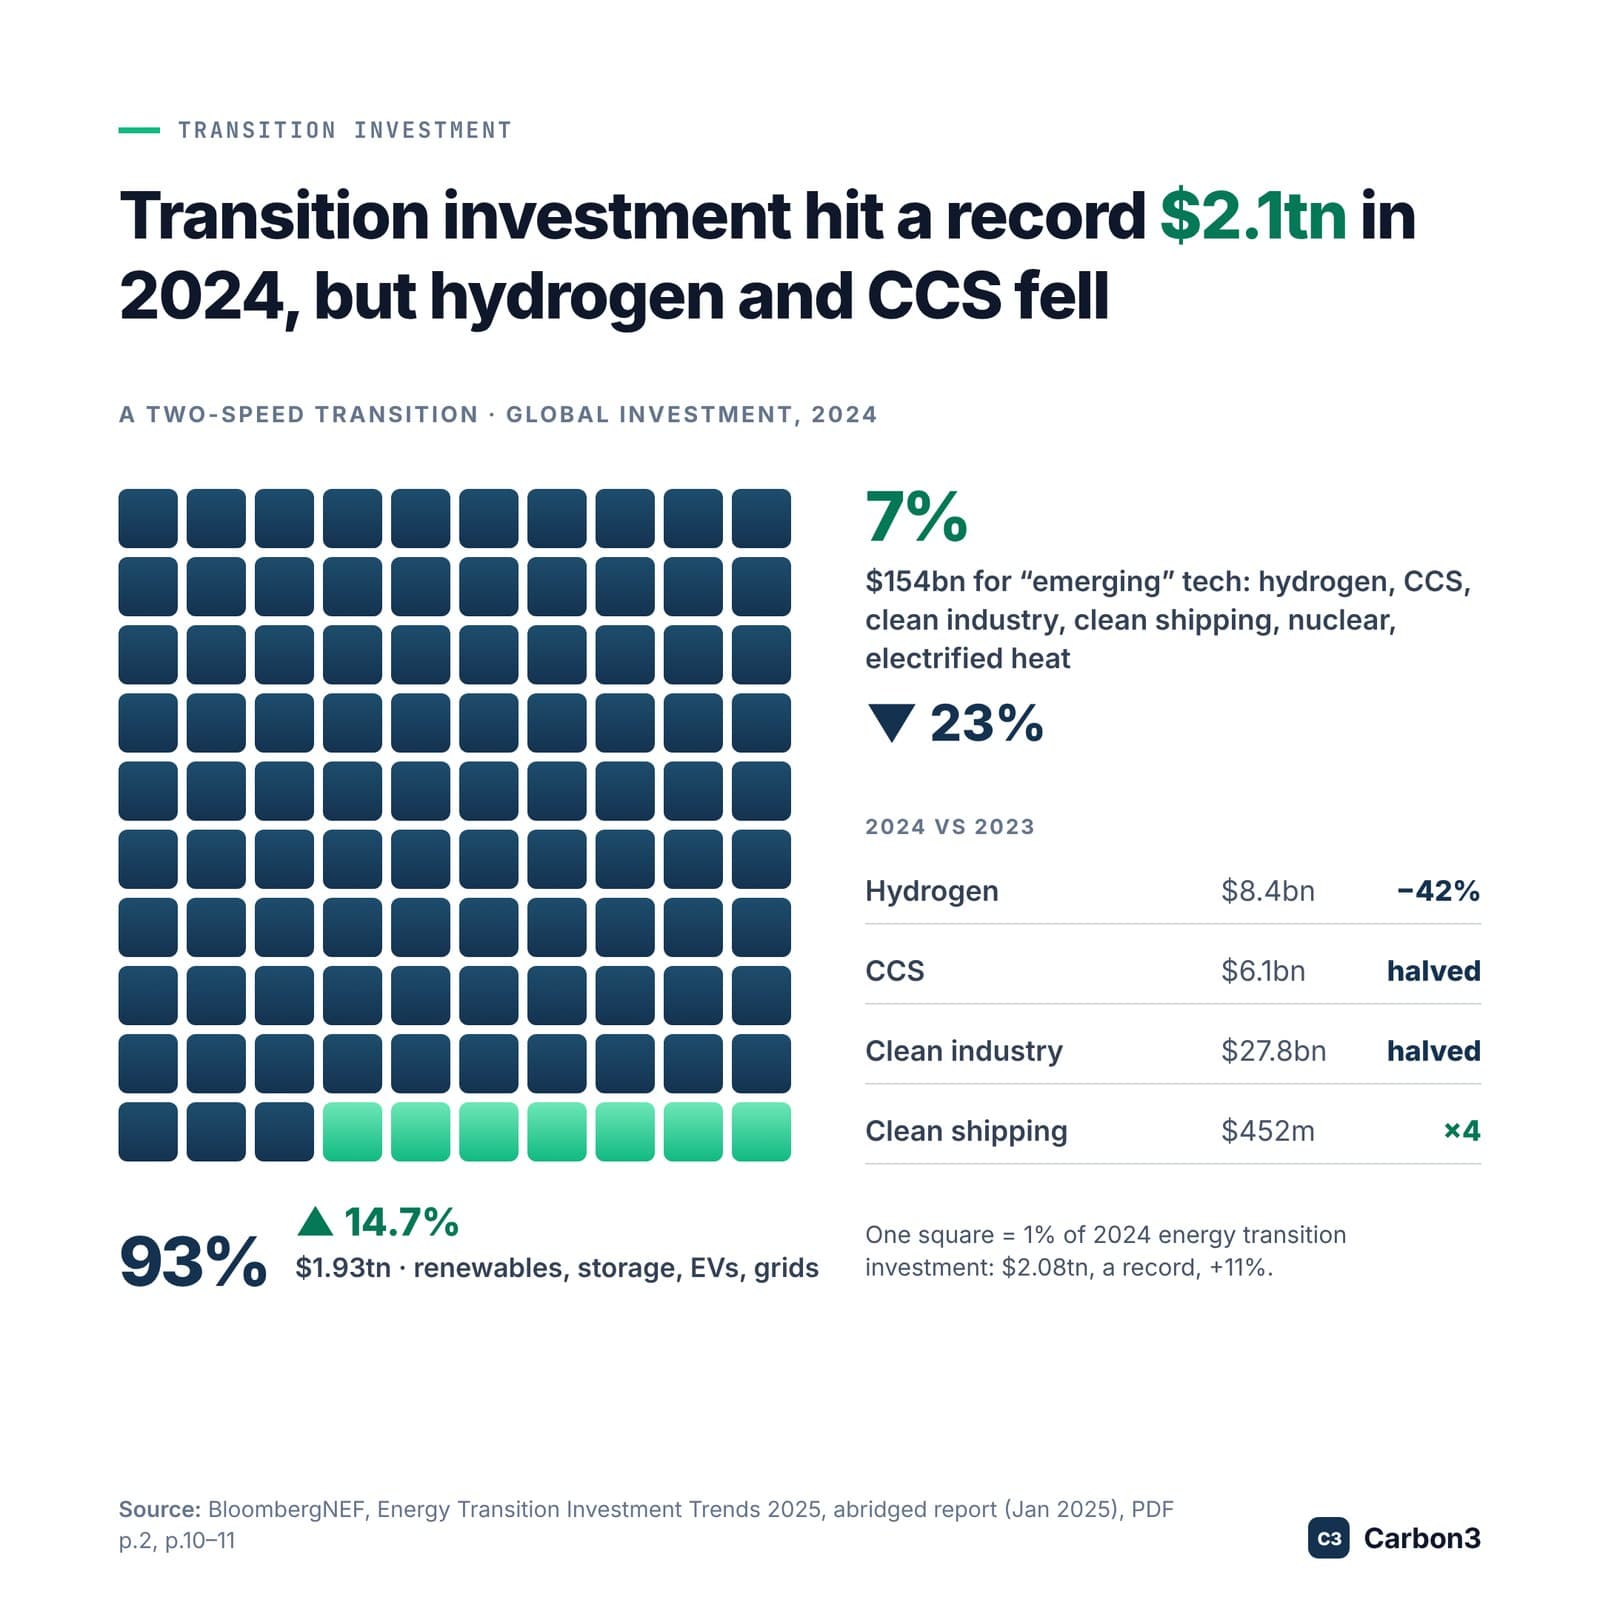
Transition investment hit a record, but not where heavy industry needs it
BloombergNEF counts a record $2.08 trillion in energy transition investment in 2024, yet hydrogen fell 42% and carbon capture and clean industry each roughly halved.
Read the articleTransition finance
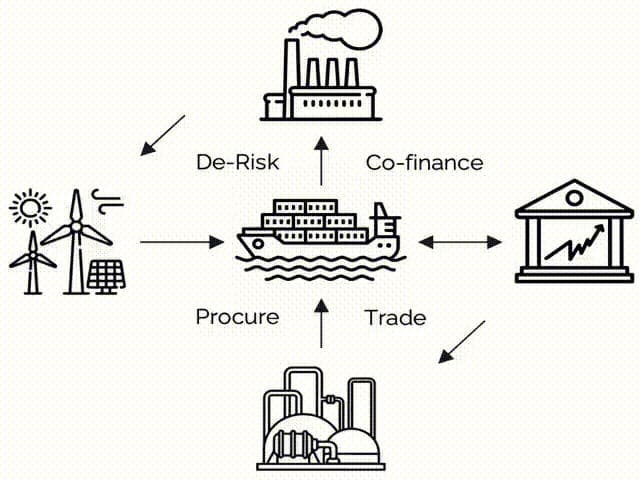
Four ways an inset credit moves capital through a value chain
Co-finance, de-risk, procure and trade: how one decarbonization project can draw on the whole value chain.
Read the articleSector: Agriculture
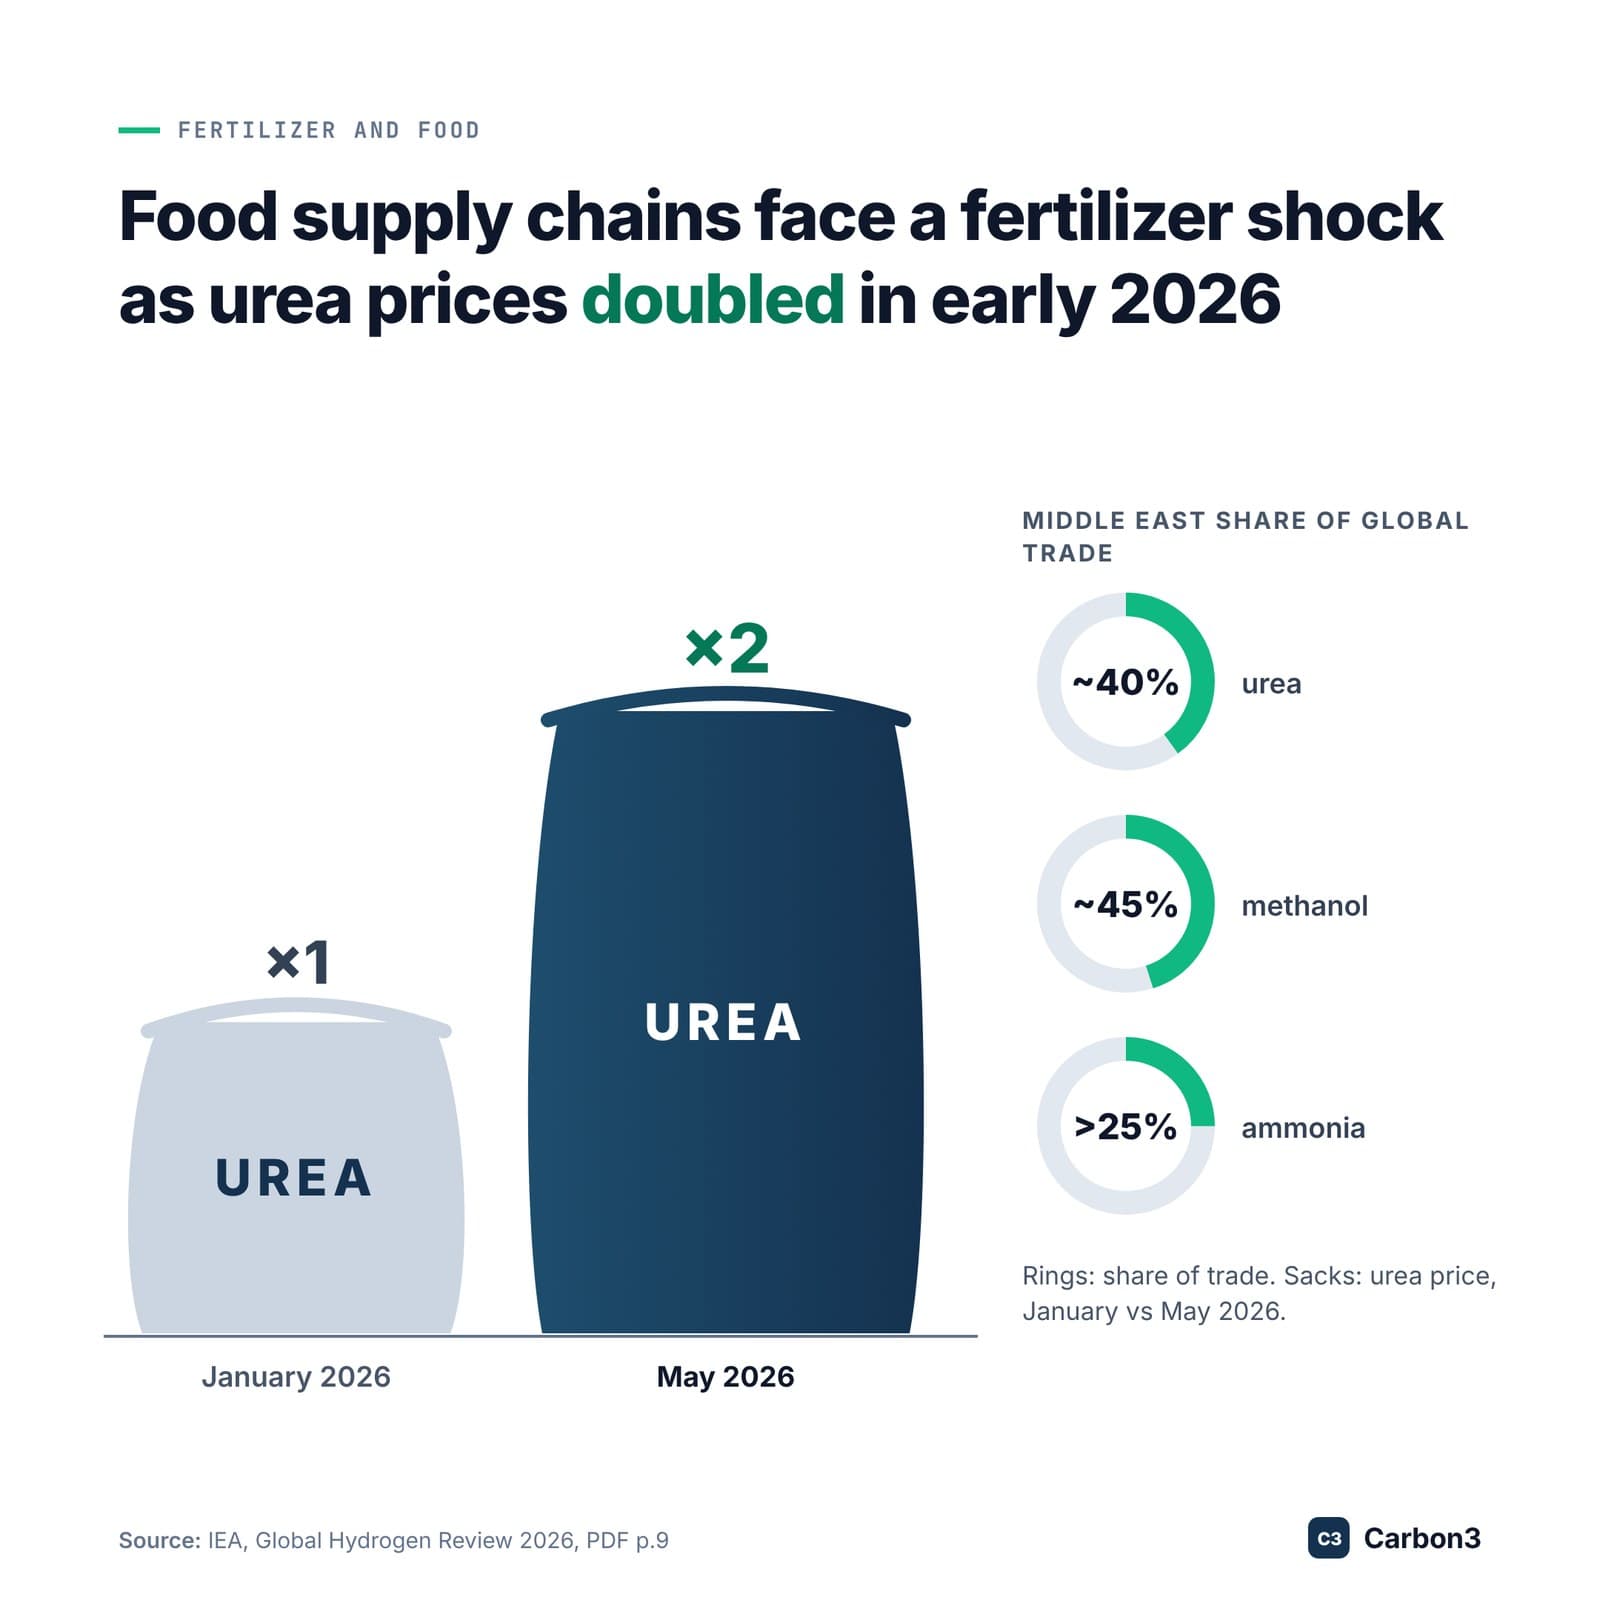
Fertilizer has become a supply-chain risk for food companies
The IEA reports that urea prices doubled between January and May 2026, which puts fertilizer in both the cost base and the Scope 3 inventory of agri-food buyers.
Read the article
See the companies behind these figures in the Data Hub.
Look up your suppliers’ emissions and targets, free.