The cost of delayed action in maritime shipping
Green fuel supply through 2030 is effectively spoken for by early movers. A late start cannot catch up.
By Carbon3 team6 min read
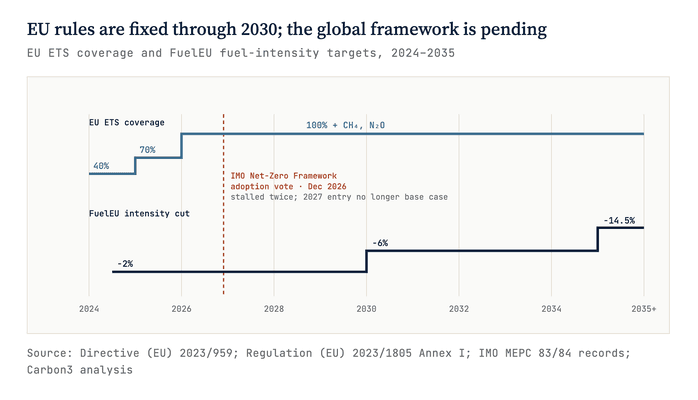
The EU now bills shipping for its carbon, and the penalty for the same shortfall grows 10% for every year it is ignored. Based on Carbon3's 2026 maritime research: what a year of delay costs the sector, a vessel, and a cargo owner.
Two sets of rules: one in force, one stalled, both costly to ignore
The European clock is already in force. Since 2024 the EU carbon market has phased in shipping, and from 2026 it covers every tonne. On top of that, FuelEU Maritime fines ships that miss their fuel targets at €2,400 per tonne of shortfall: the highest carbon price anywhere in the regime.
The global clock is stalled. The IMO's Net-Zero Framework, which would price shipping carbon worldwide, has now failed adoption twice, blocked by a US-led coalition. The next vote is December 2026, and its planned 2027 start is no longer the base case. A stalled clock does not stop the meter. Ships on EU trades pay now. Ships on global trades build up an unpriced liability that lands all at once when the framework finally passes.
The sector pays billions a year without reducing emissions
The first full EU compliance cycle put a hard number on shipping's carbon bill. Ships trading with Europe emitted about 89 million tonnes of CO₂ in 2024, and in that first year companies only had to pay for 40% of it.
From 2026 they pay for all of it. At expected carbon prices that is a bill of roughly $8.5 billion a year, rising toward $10 to $14 billion by 2030. This bill buys no abatement. Every year the fleet defers real action, it pays the full meter and starts the next year with the same emissions, at a higher price.
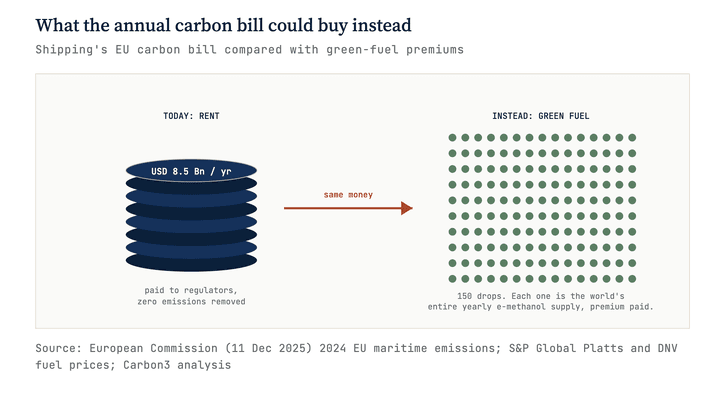
The money to close the green-fuel gap is already leaving the industry. It is going to regulators as rent instead of to fuel producers as offtake.
Penalties rise with every year of non-compliance
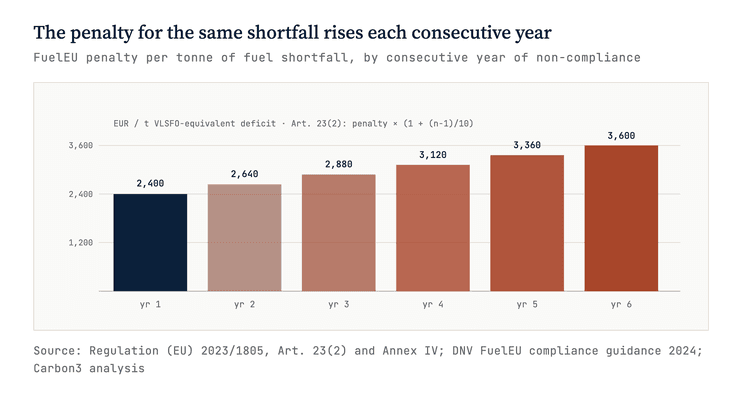
The EU fuel rules are engineered to make waiting more expensive than acting, twice over. First, the targets step up over time. Second, the penalty itself grows: a ship that misses its target in consecutive years pays 10% more for each repeat. The same shortfall that costs €2,400 per tonne in year one costs €3,600 by year six. Complying resets the counter.
What does this mean for one ship? For a large container vessel on the Asia to Europe run, burning conventional fuel, the carbon cost per round trip climbs to about two and a half times today's level by 2030. For a ship that never complied at all, the penalty multiplier pushes it close to triple. And if the global IMO framework passes, another layer lands on top.
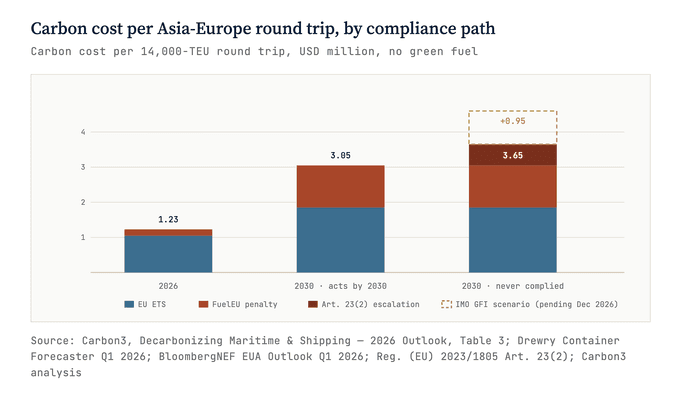
Carriers pass this through as surcharges, and those roughly double by 2030. So a cargo owner's freight bill quietly fills with carbon cost, with no claimable emissions reduction attached. Paying a surcharge is not abatement.
A delayed green-fuel program forgoes value every year
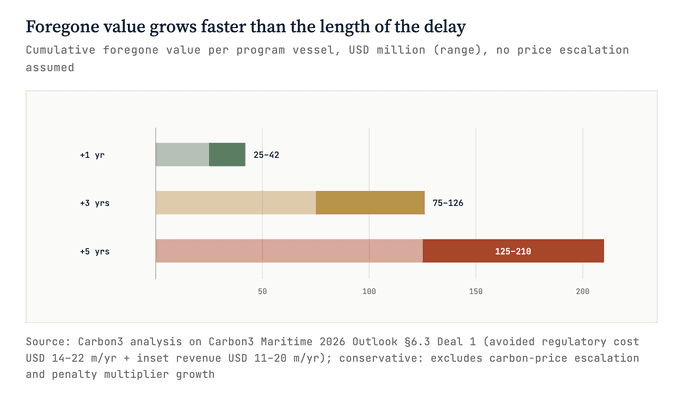
The cost of waiting is not only the meter. It is the foregone return on acting. Take Carbon3's reference case: one large container vessel running on green methanol, reducing emissions by roughly 44,000 tonnes of CO₂ a year. The moment it runs, it earns twice: $14 to $22 million a year in avoided regulatory cost, and $11 to $20 million a year in inset credit revenue, recovering a large share of the green-fuel premium.
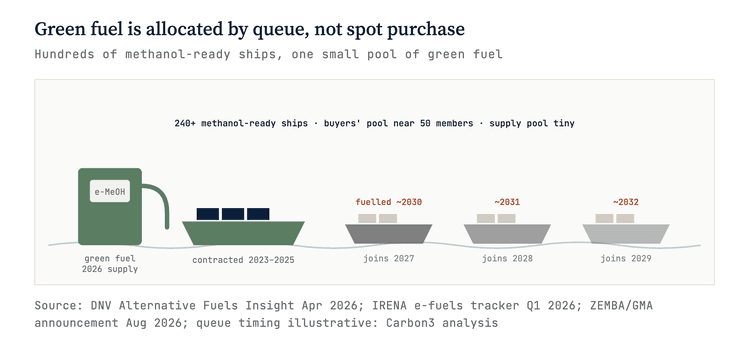
Each year the program does not run, both streams are zero. And the delay cannot be bought back later at the same price. Green fuel, and the inset credits carved from it, are allocated by queue, not spot purchase.
Why a late start cannot catch up
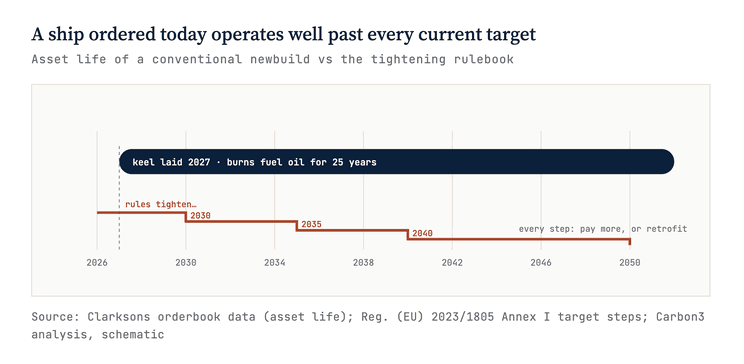
Ships last decades. The current orderbook locks vessel design in for 25-year asset lives. A conventional keel laid in 2027 burns fuel oil into the 2050s, or pays for retrofit twice.
The fuel is queued. Green fuel supply through 2030 is effectively spoken for by early movers. Latecomers face the same premium with none of the early-mover inset revenue.
Public momentum has stalled. The IMO framework is blocked, and the industry's flagship decarbonization research center cut a third of its staff this year. When regulators stall, voluntary cargo-owner demand from names like IKEA, Volvo and Cargill becomes the price-setter for green shipping. Waiting for the regulator to force the issue means arriving after the private demand pool has contracted the decade's supply.
Ember's ASEAN Power Grid analysis showed how a one-year slip compounds into a far larger five-year bill. Shipping's version is harsher in one respect: the meter is not a modeled scenario. It is invoiced, quarterly.
What early action looks like
Shipowners
Treat the growing penalty multiplier as a capital-allocation signal: one compliant year resets it. Blending, pooling and proven efficiency retrofits are all cheaper than the escalated penalty stack waiting in 2030.
Cargo owners & charterers
Convert unavoidable freight surcharges into claimable abatement: book-and-claim inset positions on green shipping lock in verified Scope 3 reductions at today's prices, while the buyer pool is fifty members, not five hundred.
Lenders
Price the delay asymmetry: a never-compliant fleet carries a compounding penalty liability and falling efficiency ratings. Covenants that reward early compliance are cheaper than repricing stranded tonnage later.
Carbon3's role is the clearing layer: verify the abatement once, allocate it across shipowner, cargo owner and lender without double-counting, and turn the green premium into a recoverable asset. The meter runs either way. Insetting decides who collects.
Methodology & sources
Derived figures labeled "Carbon3 analysis" use only cited inputs and the arithmetic shown. Sector bill: ~89.8 million tCO₂ of verified 2024 EU maritime emissions (European Commission, 11 Dec 2025) held flat, × BloombergNEF base-case EUA ($95/t 2026; $110–160/t 2030). Vessel figures: 14,000-TEU Asia–Europe round trip per Carbon3 Maritime 2026 Outlook Table 3 (Drewry Container Forecaster Q1 2026; Reg. (EU) 2023/1805 Annexes I & IV). Program vessel: 2026 Outlook §6.3 Deal 1 (ISCC EU LCA defaults 2024). Penalty escalation: Reg. (EU) 2023/1805 Art. 23(2). Green premium: e-methanol $1,650/t VLSFO-energy-equivalent vs VLSFO $540/t (S&P Global Platts Bunkerwire Q1 2026; DNV Alternative Fuels Insight Apr 2026). Cargo-owner volume of 50,000 TEU/yr is illustrative. Inset prices ($250–450) are ZEMBA-implied 2026 indications, illustrative only. No discounting applied; foregone-value totals exclude price escalation (conservative).
Full source list and citations: Carbon3, Decarbonizing Maritime & Shipping with Carbon3, 2026 Outlook, and the companion research note "The Cost of Waiting, Maritime" (August 2026). Inspired in structure by Ember, "The ASEAN Power Grid: Why every year of delay matters" (August 2026).
Originally published on LinkedIn, 30 August 2026.
The Carbon3 Newsletter
Weekly analysis of industrial decarbonization and insetting across Scope 1 to 3, from the Carbon3 team.
Read more from the research team.
Sector: Maritime
Book and claim for maritime decarbonization: momentum and fragmentation
The model is gaining traction with buyers and standards bodies, but inconsistent frameworks push a heavy due-diligence burden onto procurement teams.
Read the articleSector: Maritime
Ten years of the Clean Marine Fuel Forum
No single fuel or pathway to net zero, but progress cannot wait for perfect certainty.
Read the articleSector: Maritime
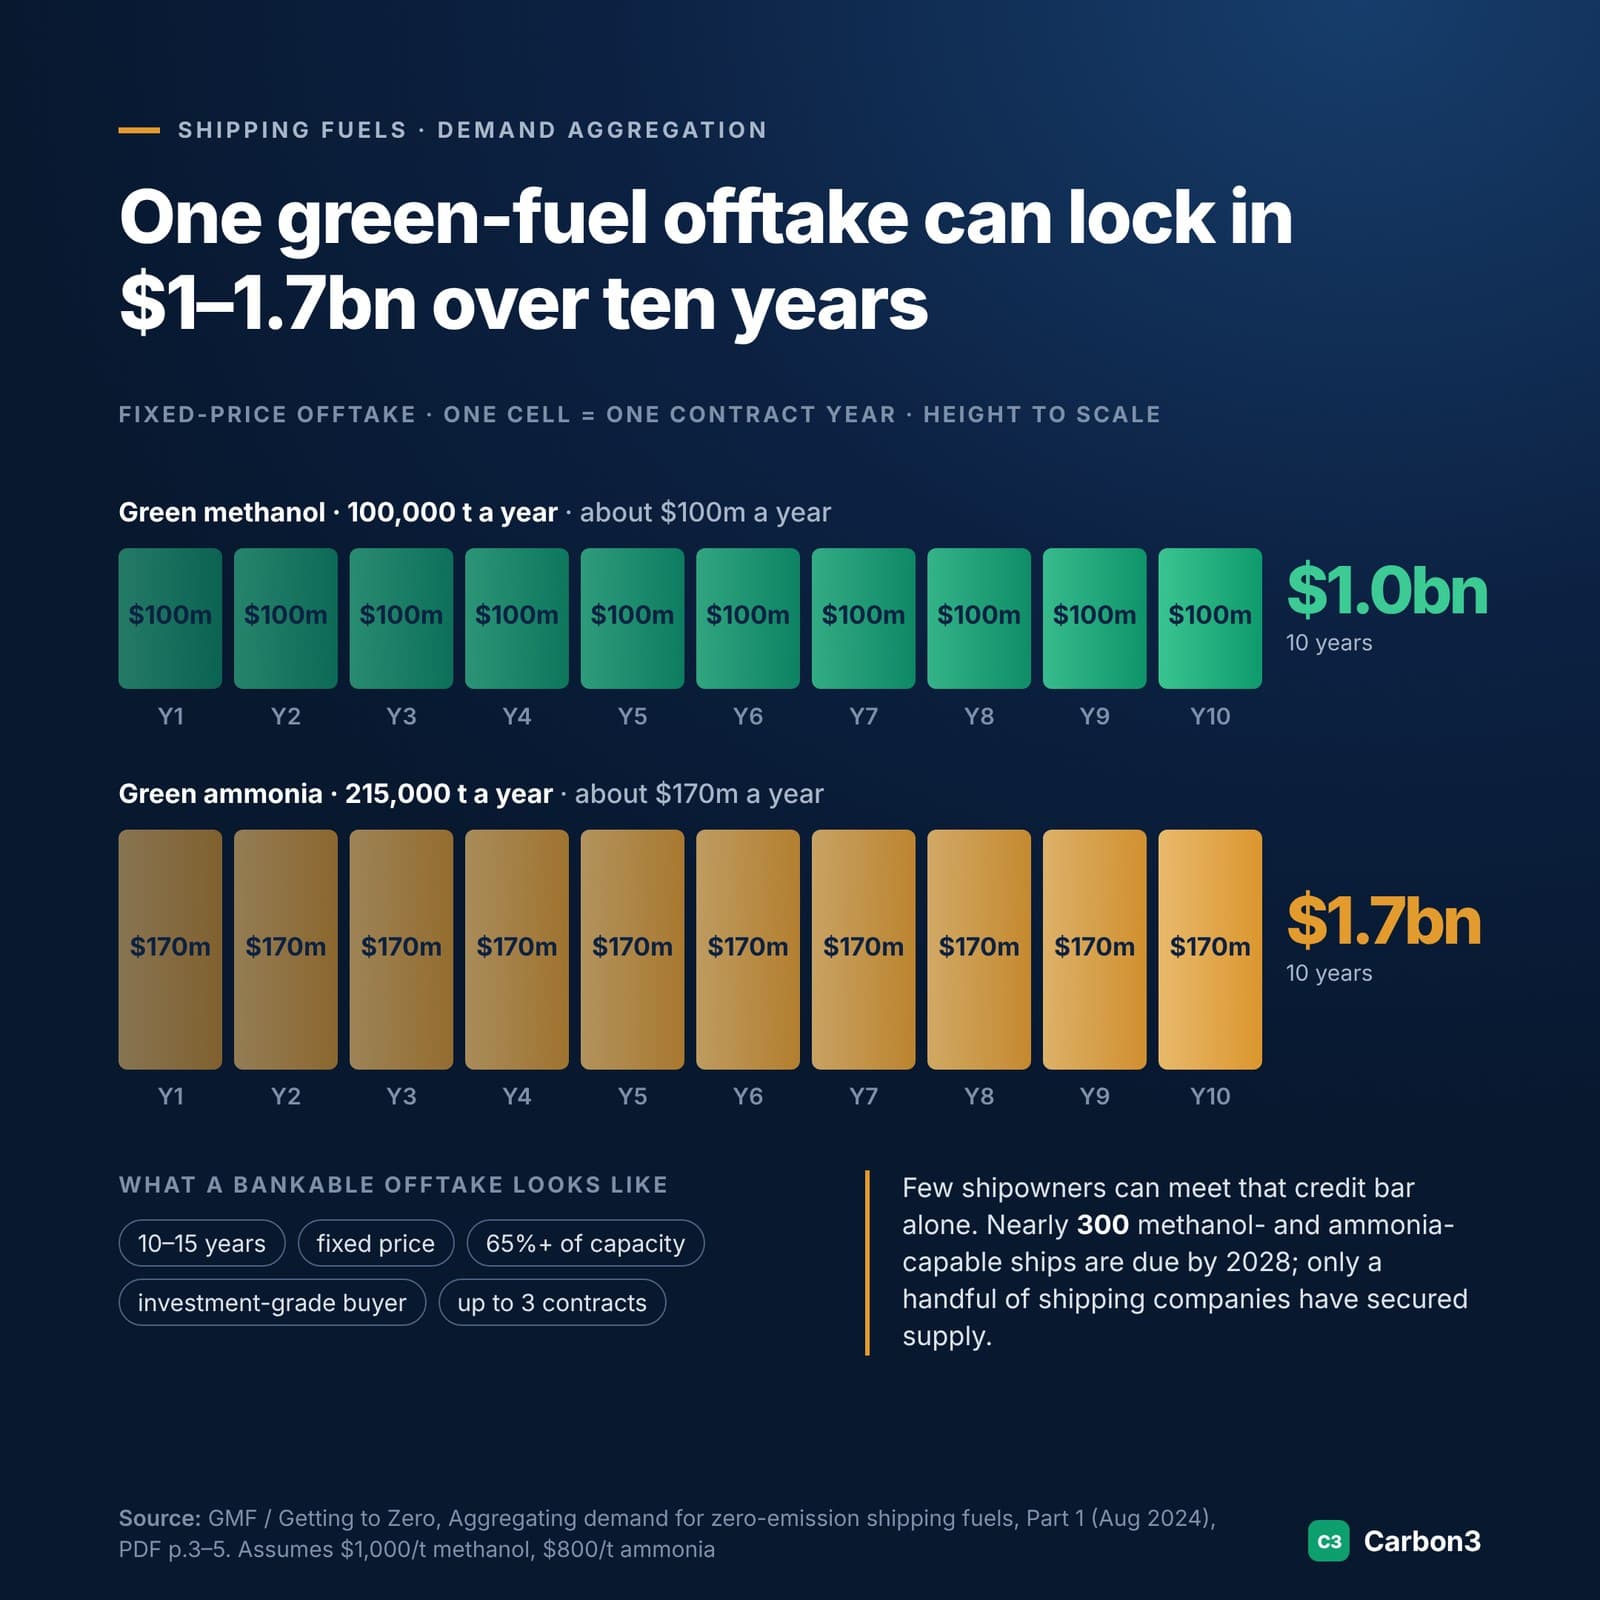
One green shipping fuel contract can commit a buyer to $1 billion or more
The Global Maritime Forum and the Getting to Zero Coalition price a 10-year green methanol or ammonia offtake at $1 billion to $1.7 billion, while nearly 300 capable ships are due by 2028.
Read the article
See the companies behind these figures in the Data Hub.
Look up your suppliers’ emissions and targets, free.