The EU's Temporary Decarbonisation Fund has an inverted incentive
The Court of Auditors warns that retroactive, history-based payouts deliver weak steering power. The same flaw plagues most supplier programs.
By Carbon3 team2 min read
The EU’s Temporary Decarbonisation Fund aims to mitigate carbon leakage by recycling CBAM revenues into heavy industry. However, the European Court of Auditors (ECA) has cautioned that the fund’s conditions for support may not yield the intended climate impact.
To qualify for funding, companies must implement energy audits or climate neutrality plans. Yet, because the financial support is calculated against historical production and paid retroactively, the ECA warns that this poses a "risk to sound financial management." The incentive structure is inverted: companies are reimbursed long after operational decisions are made, drastically reducing the fund's steering power over new investments.
This structural critique is highly relevant to Scope 3 decarbonization strategies. Reimbursing suppliers retroactively is an inefficient way to alter supply chain behavior. Instead, pricing the green premium at the point of transaction is required. Auditable insetting architectures address this by issuing verifiable units tied to strict additionality, ensuring that the financial incentive precedes the action and maps correctly to commercial flows.
Even with billions in recycled CBAM revenues flowing back to heavy industry, the fund’s retroactive, history-based payouts deliver weak steering power and limited real decarbonization impact. The same inverted incentive plagues most corporate supply-chain programs today: paying suppliers after the fact for past reductions rarely shifts future procurement behavior or capex.
How Carbon3 can help: by operating a verified insetting marketplace that prices the verifiable green premium at the point of transaction, issuing tradable, additionality-backed inset credits that suppliers can monetize upfront, buyers can embed in contracts, and both sides can allocate and report inside the Scope 3 boundary.
In short, Carbon3 turns sustainability spend from an ex-post accounting exercise into a proactive, bankable commercial signal that actually drives new low-carbon investment while strengthening your CBAM resilience and ESG credibility. Early adoption here positions you ahead of both regulators and competitors who are still relying on blunt, backward-looking tools.
European Court of Auditors European Commission Publications Office of the European Union
ECA Opinion 13/2026 (Temporary Decarbonisation Fund): eca.europa.eu
EUR-Lex proposal PDF: eur-lex.europa.eu
Learn more
How the standards apply to inset credits
Originally published on LinkedIn, 14 April 2026.
Read more from the research team.
Policy
California's SB 253 sets the first Scope 1 and 2 deadline for August 2026
Scope 3 reporting follows in 2027 for large entities doing business in the state.
Read the articlePolicy
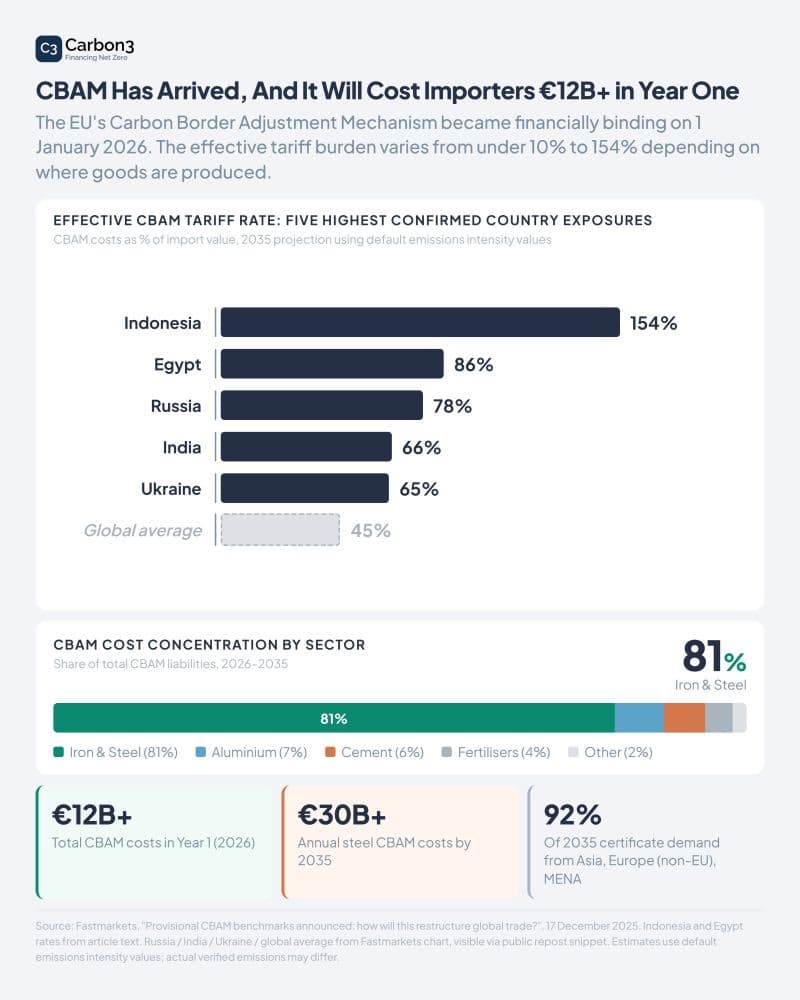
CBAM liabilities are concentrated in steel and in a few exporting countries
Some exporters face tariff-equivalent exposure far above the global average.
Read the articleSector: Maritime
The EU wants to pay most of shipping’s clean fuel premium, and cargo owners would fund the rest
A proposed reserve of 110 million carbon allowances would narrow the price gap for green marine fuels, which makes the question of who claims the reduction more pressing.
Read the article
See the companies behind these figures in the Data Hub.
Look up your suppliers’ emissions and targets, free.