Agrifood emissions growth has shifted to packaging, shipping, waste and retail
On-farm practices remain the largest driver, but pre- and post-production services deserve closer attention for their Scope 3 impact.
By Carbon3 team1 min read
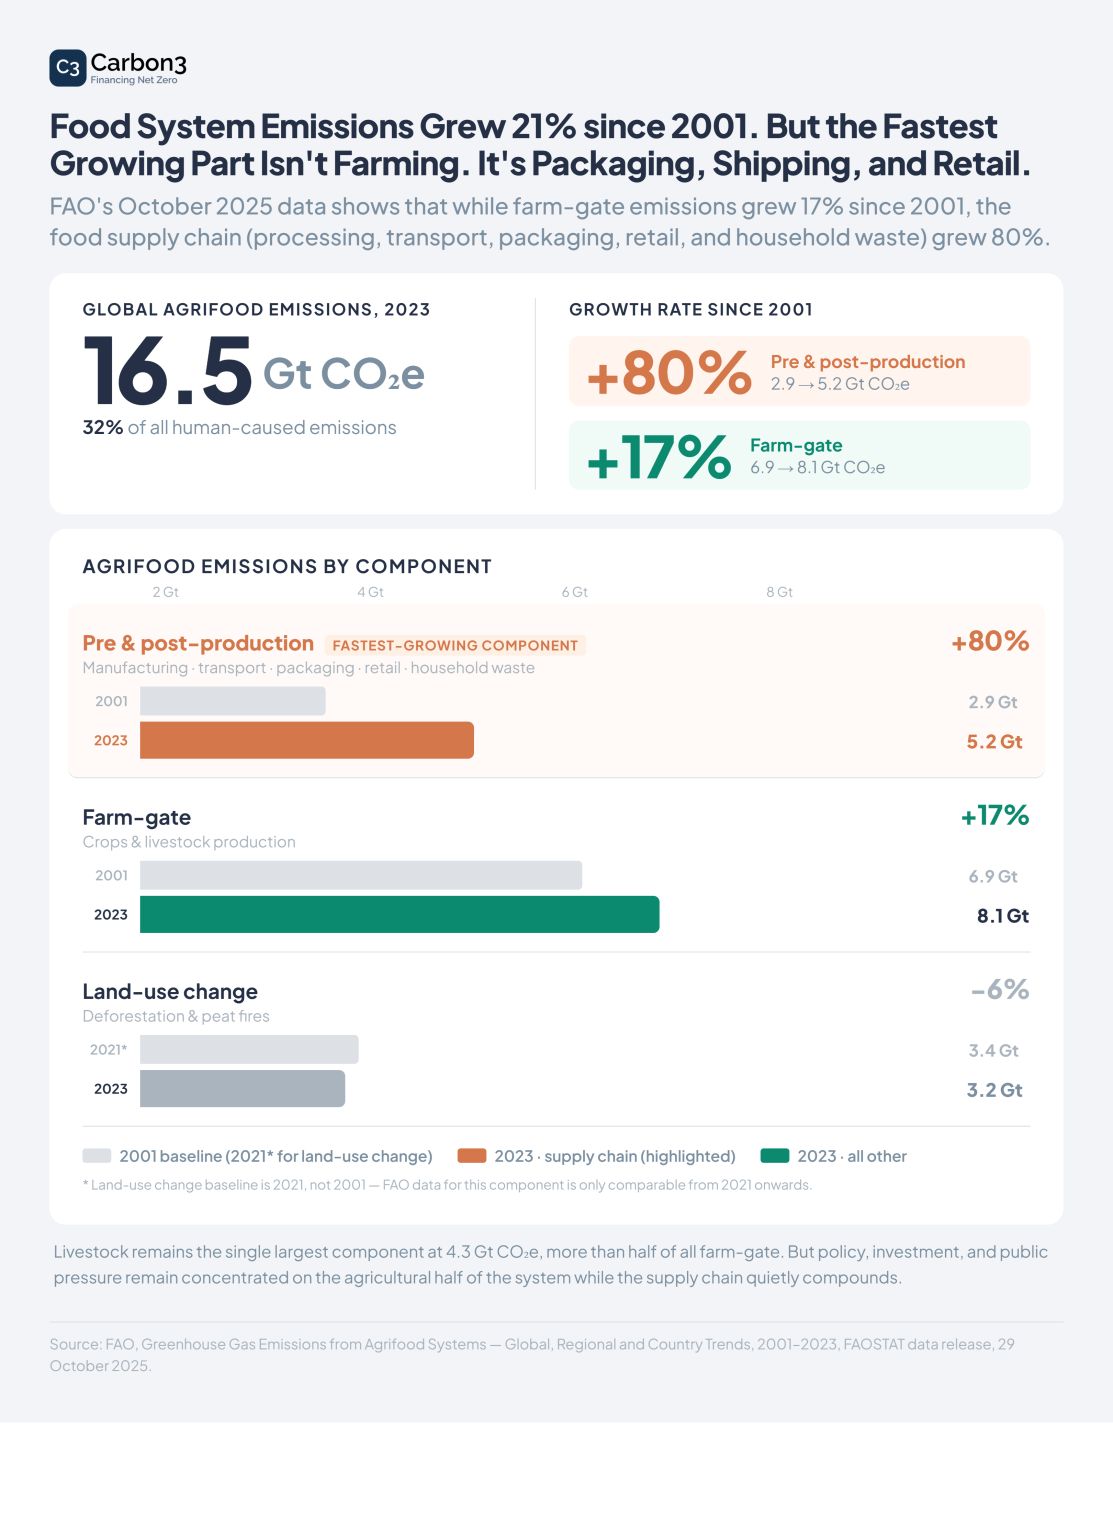
Over the past 20+ years, the greatest growth in emissions in agrifood systems has actually been in packaging, shipping, waste, and retail handling. While on-farm practices remain a major driver of emissions, the pre- and post-production services deserve closer attention for how they impact the upstream Scope 3 emissions of the agricultural sector.
The shift changes where a food company should look for reductions. Farm-level interventions are still the largest opportunity in absolute terms, but they are slow to scale and hard to measure across many small producers. Packaging, cold chains, logistics and retail handling are concentrated in fewer hands, better instrumented, and often cheaper to change.
Both layers can be financed the same way. A retailer or brand that funds a supplier's switch to lower-carbon packaging or electrified distribution can claim the verified reduction against its own Scope 3 inventory, and the supplier recovers part of the cost through the same transaction. Insetting is agnostic about where in the chain the reduction sits.
Learn more
How insetting works in food and farming
Originally published on LinkedIn, 8 June 2026.
Read more from the research team.
Sector: Agriculture
Yara: cost discipline and decarbonization as one agenda
Record operational performance alongside 42.6 million tCO2e of Scope 3.
Read the articleSector: Agriculture
Supermarkets are struggling with food emissions
Madre Brava's UK director on why farm-level change is too slow and too small to hit near-term retail targets.
Read the articleSector: Maritime
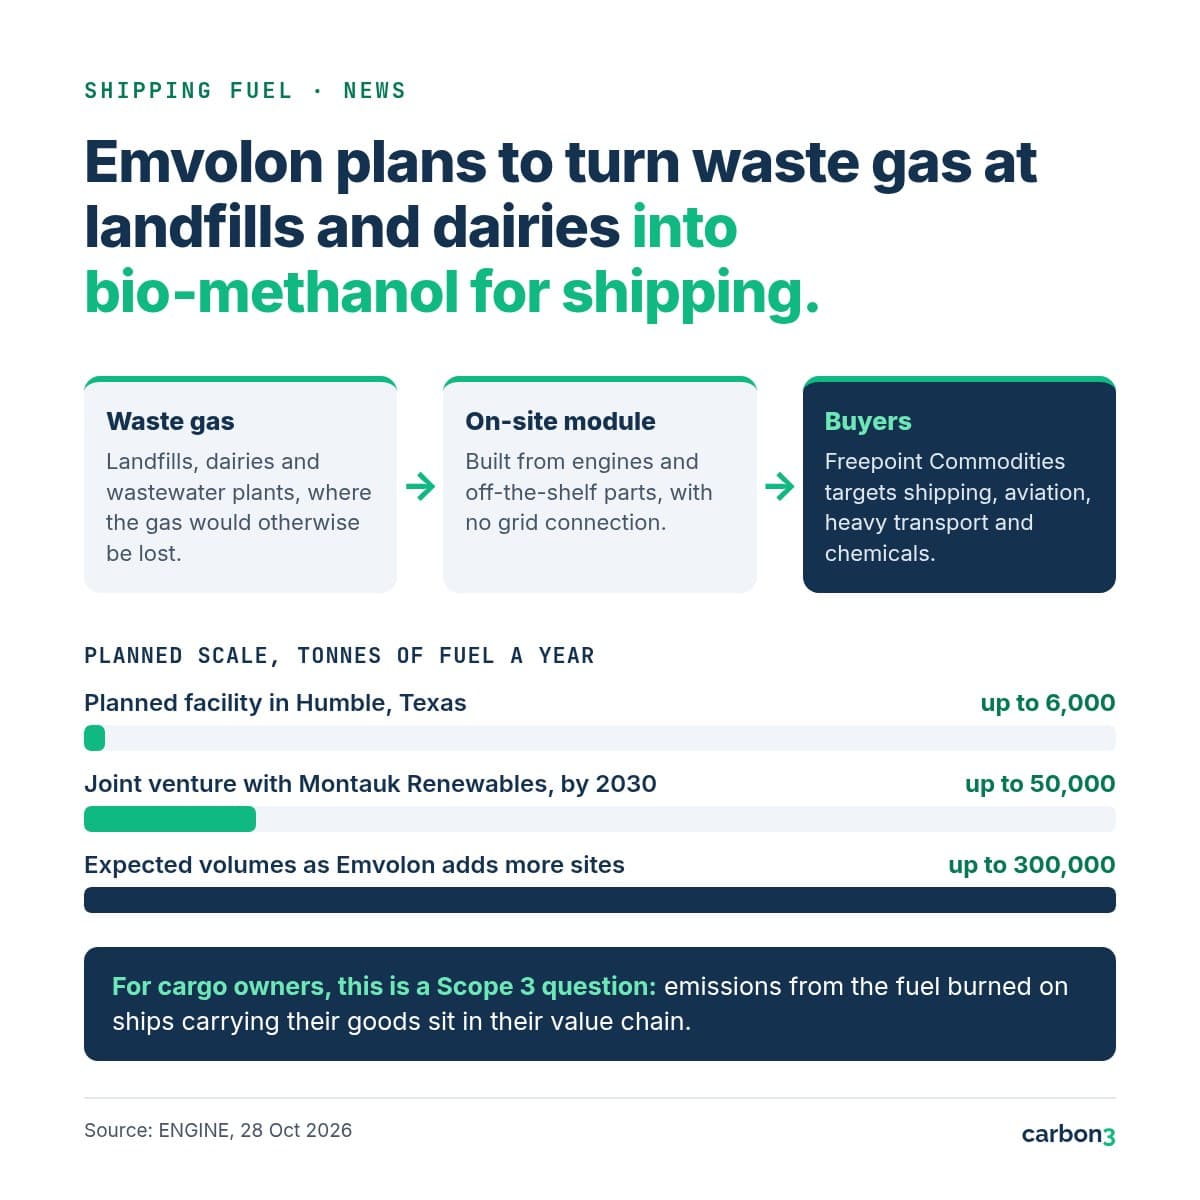
Emvolon will turn waste gas into bio-methanol for shipping
The US start-up will build its first commercial plant with a $22 million Series A round and government grants, and Freepoint Commodities holds a first purchase option on up to $450 million worth of its fuel.
Read the article
See the companies behind these figures in the Data Hub.
Look up your suppliers’ emissions and targets, free.